Author: Antonis Alexandrou, Project Manager
Think back to the last time you opened a new bank account, applied for a credit card, or set up an account with an online investment app.
You probably had to upload pictures of your driver’s license, snap a selfie, answer a long list of personal questions, and then wait. Sometimes you waited a few hours. Other times, you waited days. If you were opening an account for a business, that wait could easily stretch into weeks while bank employees hunted through public registers to prove your business was legitimate.
For a long time, banks and financial institutions operated under a simple assumption: keeping things safe meant making things slow. To stop money laundering, identity theft, and fraud, customers had to deal with paperwork and friction.
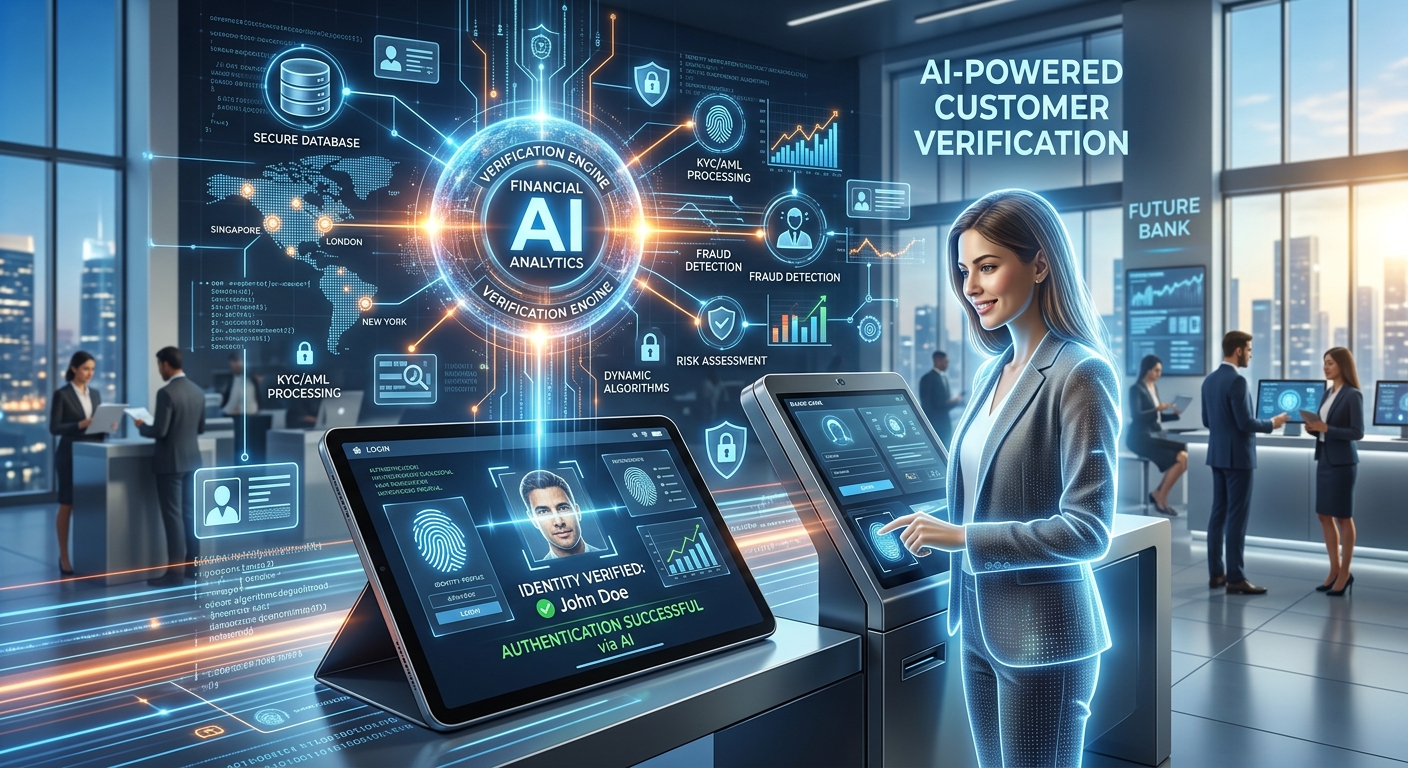
Today, that trade-off is disappearing. Driven by smarter fraudsters, stricter government rules, and our demand for instant service, Artificial Intelligence is completely changing how financial companies verify who you are and onboard you as a customer. What used to be a time consuming exercise is turning into something fast, smart, and continuous.
The Problem with the Old Way of Doing Things
To understand why AI is taking over, it helps to look at why the traditional verification system, often called Know Your Customer, or KYC is breaking down.
The old setup was built for a world where people walked into physical bank branches with paper documents. When everything moved online, banks essentially took those paper processes and pasted them onto screens. That caused three major headaches:
- Frustrated Customers: When signup forms are long and confusing, people simply give up. High value customers abandon the application halfway through and go to a competitor who offers a smoother signup.
- The “False Alarm” Problem: Old computer software relied on rigid rules. If your name is John Smith and a known fraudster named John Smith shows up on a watch list, the system flags your account. Thousands of innocent people get flagged every day because of simple typos or common names, burying bank workers under mountains of useless alerts.
- Fakes Are Getting Better: Scammers now use digital tools to create hyper-realistic fake IDs and videos. Standard checks that used to catch impostors can easily be tricked by a convincing synthetic identity or a generated video.
How AI Makes Verification Faster and Safer
Modern AI tools don’t just look for exact matches in a database. They look at pictures, patterns, and language much like a human expert would, only in a fraction of a second. Here is where AI is stepping in to fix the onboarding process:
1. Reading Documents Automatically
Instead of requiring a human employee to look at your driver’s license or passport and manually type your information into a computer, AI software can read and verify documents instantly. It checks the text, translates different languages on the fly, and examines the image down to the pixel level to make sure the document hasn’t been altered or photoshopped.
2. Catching Fake People and Deepfakes
To prove you are actually you, many apps ask you to take a short video selfie. To stop scammers from holding up a photo or playing a fake video, AI looks at micro movements for example how light reflects off your skin, natural eye twitches, and 3D depth. It can tell the difference between a live human being sitting in front of a phone and a computer generated trick.
3. Unravelling Complex Business Ownership
Verifying an individual person is one thing, verifying a company is much harder. Businesses are often owned by parent companies, which are owned by holding groups across different countries. In the past, bank analysts spent days digging through corporate filings to figure out who actually owned the business. AI tools can analyse complex web networks of corporate ownership in minutes, instantly showing who is behind the curtain.
Checking Once vs Checking Always
One of the biggest changes happening behind the scenes is a move toward Perpetual KYC or continuous verification.
In the past, banks checked your information when you opened your account, and then they didn’t look at you again for three to five years unless something went drastically wrong. But a lot can happen in three years. A company might change owners, an individual might move to a high risk location, or a person’s financial background might change overnight.
| Feature | Old Verification Method | AI Powered Continuous Verification |
| How Often Checks Happen | Once every few years on a fixed schedule | Constantly in the background |
| When Alerts Are Raised | Long after a problem occurs | Instantly when something changes |
| Inconvenience to You | High (filling out forms repeatedly) | Very Low (happens automatically) |
| Sanctions & Risk Watch | Checked periodically in batches | Updated live as rules change globally |
With AI running in the background, verification becomes an ongoing safety net rather than a onetime gate. The system continuously scans public risk databases and transaction patterns. If nothing unusual happens, you never hear about it. But if an actual risk pops up for example a sudden link to an international sanctions list, the system flags it right away.
Keeping the Human Touch and Staying Fair
With all this talk about automation, it’s fair to wonder: are computers going to make all the decisions about who gets a bank account and who gets turned away?
The short answer is no, and for a good reason.
Regulators require financial institutions to explain why a customer was turned down or flagged. A computer program that just says “Denied” without explaining itself is a massive legal liability. If an AI system relies on bad historical data, it could also accidentally discriminate against certain groups of people.
That’s why the future of finance relies on Explainable AI and Human-in-the-Loop systems:
- Transparent Reasoning: Instead of just giving a thumbs-up or thumbs-down, the AI gives a clear reason for its suggestion for example, “Name matches a watchlist entry with 85% confidence, but address does not match”.
- Humans Make the Hard Calls: AI handles the straightforward, obvious cases which make up the vast majority of applications. When a case is complicated, unusual, or sensitive, the system hands it over to a human compliance expert to make the final decision.
What This Means for Everyone
The shift toward AI-powered verification isn’t just about saving banks money or making life easier for compliance teams. It directly changes how we interact with the financial world.
For regular consumers, it means opening an account in two minutes from a couch without sending endless emails. For businesses, it means getting access to loans, payment systems, and bank accounts in hours instead of months. And for society as a whole, it means financial systems become much harder for fraudsters and criminals to exploit.
By turning verification from a slow, paper-heavy chore into a fast, smart background process, AI is proving that staying safe doesn’t have to mean standing in line.
Comments are closed